
Vea también


 14.10.2026 10:11 AM
Asian indices fell after chip-equipment maker ASML said it won't be able to fully meet demand, reviving concerns about the AI trade. The MSCI Asia Pacific slipped by 0.1% after earlier gains of 0.7%. Nasdaq 100 futures turned negative, and S&P 500 and European contracts gave back most of their advances. The dollar eased ahead of key US inflation data.
ASML's update is mixed. The company warned it cannot fully satisfy demand over the next two years, yet it raised the lower end of its 2026 revenue guidance. The news hit South Korea hardest: the Kospi, a barometer for AI and semiconductor investment, fell by 1% after rising by 2.6% earlier in the session. That's unsurprising given how sensitive Korea's market is to doubts over whether massive AI spending will deliver proportional returns. Right now, any news that suggests friction in the sector is felt more acutely than positive corporate forecasts.
Chinese markets are under pressure as well. The CSI 300 dropped by 0.3% to its lowest level since August 2025 and is down more than 15% from its June peak, approaching bear-market territory. Investors are increasingly skeptical that large-scale stimulus will revive growth.
Oil adds to the uncertainty. Brent rose by 0.6% to $106.30/bbl from roughly $105 the previous day, and US crude extended a five-day gain. A fresh wave of attacks in the Middle East has strengthened doubts about a quick restoration of Persian Gulf flows. That's bad for inflation: higher oil fuels price pressures, making the Fed's task harder and complicating hopes for a dovish pivot.
That's why all eyes are on the US CPI report. Economists expect headline monthly inflation to rise by 0.6% after an increase of 0.4% the prior month, the strongest monthly gain in five months. Comments from New York Fed President John Williams, who allowed for another interest rate increase this year but saw no need for further tightening in 2027, slightly eased sentiment.
The bond market is relatively calm for now. The 10-year Treasury yield is about 5.20% after 5.31% on October 8. Gold is holding near $4,160/oz, a touch below Tuesday morning's $4,192 high.
In my view, if CPI prints at or below 0.6% month-on-month, dollar pressure should continue, yields may drift lower, and Asian stocks would have a chance to bounce, though semiconductors will remain vulnerable given the ASML news. If inflation surprises to the upside, bets on further hikes will return, the dollar will strengthen, and risk appetite will suffer, particularly in Asia and stocks exposed to AI. Given the current backdrop of high oil prices and capital outflows from the region, I expect any rebound to be muted. Without a sustained drop in oil prices, Asian equities are likely to lag.
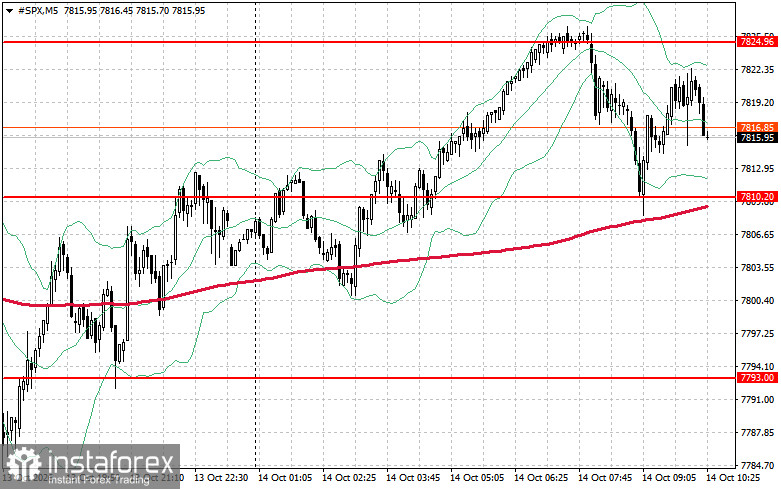
As for S&P 500 technicals, the immediate task for buyers today is to overcome the resistance level of $7,824. That would show upside momentum and open the path toward $7,841. Holding $7,862 is also a priority for bulls to solidify positions. If the price moves lower amid falling risk appetite, buyers must show up around $7,810. A break below that level would likely push the index down to $7,793 and open the way to $7,774.


